Ethereum Tanks to 2-Month Low: Whales Return but Sub-$2K Fears Mount
Ethereum's price has fallen to a two-month low, raising fears of further declines.
CryptoPotato1 min read
The UK is updating its payments regulations to facilitate the use of stablecoins and tokenized deposits. HM Treasury announced plans for a single framework for traditional and digital payment services.
Mentioned in this story
The United Kingdom is revisiting its payments rulebook to support the adoption of new fintech and payment technologies such as stablecoins and tokenization.
In a Tuesday announcement, HM Treasury and Economic Secretary to the Treasury Lucy Rigby said the government will consult on reforms for payment services and electronic money rules.
The Treasury said the changes are meant to create a single framework for traditional and tokenized payments, including stablecoins and tokenized deposits. It also said it plans to bring forward legislation to reduce administrative burdens for companies seeking to offer stablecoin payment services.
The Treasury also named former Financial Conduct Authority veteran Chris Woolard as digital markets champion for its Wholesale Financial Markets Digital Strategy, where he will support efforts to drive adoption of tokenized digital assets.
Woolard highlighted the growing role of digitization in financial markets, emphasizing that collaboration and a dialogue between the private and public sectors will best support the UK’s global competitiveness as a leader in digital markets.
The package comes as the UK continues to develop its broader crypto regulatory framework, with legislation expected to take effect in 2027.
The new package was unveiled during UK Fintech Week in London, a series of industry events supported by organizations such as Innovate Finance, the independent industry body for the UK fintech sector.
A key part of the plan is bringing stablecoins and tokenization more deeply into the payments system, including through regulatory reform as a core measure.
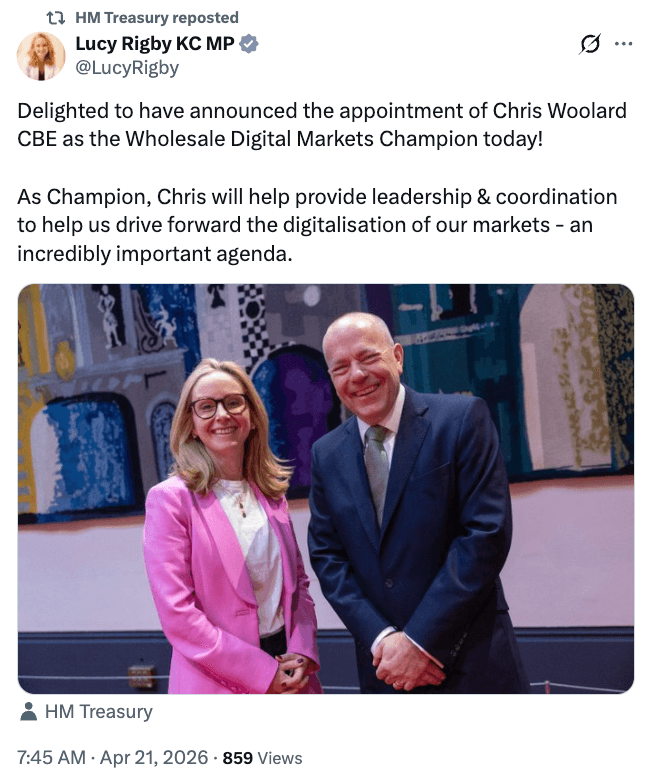
Source: Lucy Rigby
“This will mean establishing a single, coherent framework for both traditional and tokenised payments, including both stablecoins and tokenised deposits,” the announcement said.
The UK government is consulting on reforms to create a unified framework for traditional and tokenized payment services, including stablecoins.
Chris Woolard, a former Financial Conduct Authority veteran, has been appointed as the digital markets champion.
The new rules aim to reduce administrative burdens for companies seeking to provide stablecoin payment services.
Ethereum's price has fallen to a two-month low, raising fears of further declines.
Peter Schiff issues a stark warning about Bitcoin's $60,000 price floor, calling it a 'trap door'.

Analyst predicts Bitcoin won't bottom until it hits EMA 300 level.
We asked AI if XRP can surpass $2 again. The answers were surprising!
XRP Ledger Foundation hints at upcoming version 3.2.0 release.

Bitcoin's recent momentum signals a potential downturn as it weakens. What does this mean for investors?
See every story in Crypto — including breaking news and analysis.
The Treasury also said it wants to reduce administrative burdens for companies seeking to offer stablecoin payment services in a move to “cement the UK as a world-leading destination for digital assets.”
Another part of the package is the government’s decision to explore how payment regulation should apply when AI agents make transactions on behalf of consumers or businesses.
Philip Belamant, co-founder of Zilch, an FCA-authorised consumer credit fintech listed among key stakeholders, said that AI will “fundamentally change how people interact with money,” shifting payments to something that is managed in the background.
“As this becomes a reality, it’s critical that regulation evolves to support innovation while maintaining strong consumer protections,” he said.